
Sell a house with liens or title issues in Massachusetts
A lien or a clouded title can make a home feel impossible to sell, but it usually is not. We buy houses across Massachusetts as-is, for cash, and our title team is used to working through liens and title problems so you do not have to untangle them alone.
- Most liens are paid off from the sale proceeds at closing, not out of your pocket up front
- Our title team is used to working through liens and clouded title
- We buy as-is for cash — no repairs, no fees, no commissions
Offer request received
We’ll review your property and reach out shortly.
Yes — you can usually sell a Massachusetts house that has liens or title problems on it. In most cases the liens are paid from the sale proceeds at closing by the closing attorney and the releases are recorded, so you are not paying anything off up front. We buy as-is for cash, give you a written no-obligation offer within 24 hours, and work alongside the closing attorney and title team to clear what is recorded against the property.
Updated September 2026
We buy houses with liens and title problems in Massachusetts
Few things make a house feel more stuck than finding out something is recorded against it. You are ready to sell, and then a title exam turns up a judgment you forgot about, a contractor’s lien from a job that went sideways, or a mortgage that was paid off in 2009 and never properly discharged. The house is yours and not quite yours at the same time.
The reassuring part is how ordinary this is. Liens and clouds on title come up constantly in Massachusetts real estate, and there is a well-worn process for handling most of them inside a normal closing. You do not need to become an expert in conveyancing, and you almost never need to write a check before anyone will talk to you.
New England Home Partners buys houses across Massachusetts as-is, for cash. Written no-obligation offer within 24 hours, a closing date you choose, and a title team that is comfortable working through recorded claims alongside the closing attorney. Our full walkthrough of clearing a lien or title problem before selling has the detail behind everything below.
What counts as a lien or a title issue
A lien is a recorded claim against the property, usually for money owed, that generally has to be resolved before clear title can pass. A title issue is anything that muddies the chain of ownership or leaves doubt about who can convey the house. The ones we see most often:
- Judgment liens — recorded at the Registry of Deeds after a court judgment for a debt.
- Contractor or mechanic’s liens — filed by a contractor or supplier claiming they were not paid for work on the property, under the Massachusetts mechanic’s lien framework, which has strict procedural requirements.
- Municipal charges — unpaid real estate taxes, water and sewer, and similar items, which show up on the municipal lien certificate the closing attorney orders from your city or town.
- State and federal tax liens — a Department of Revenue lien for unpaid state taxes, or a Notice of Federal Tax Lien from the IRS. Our guide to selling a house with back taxes or a tax lien explains how each behaves.
- Condominium or HOA liens — for unpaid association dues or assessments.
- Old mortgages never discharged — a loan paid off years ago but never released in the records, so it still appears to encumber the house.
- Probate and heirship gaps — uncertainty about who inherited the property or who has authority to sign, which is common when a deed still names someone who has died. Selling an inherited house in probate covers that path.
- Deed and boundary defects — a scrivener’s error in an old deed, a missing signature, an easement nobody remembered, or an unclear property line.
You do not need to diagnose which applies to you. Sorting that out is precisely what a title exam and a closing attorney are for.
How liens usually get paid at closing
In most sales, you do not pay the liens off yourself beforehand. The closing attorney identifies everything recorded, requests a written payoff figure from each claimant that is good through a specific date, and pays them from the sale proceeds at the closing table. The releases or discharges are then recorded so the title is clear for the new owner. Whatever remains after the payoffs and costs is your equity.
That is why a lien is often a line item rather than a wall. If the house is worth more than the total recorded against it, there is usually money left for you. If it is not, options exist — a negotiated release for less than the full balance, or, in the federal tax case, an application for a certificate of discharge that removes the lien from that one property so the sale can close. The IRS explains the federal lien process at irs.gov. These are attorney matters, not web-page matters, so consult a Massachusetts attorney about your specific payoffs.
How a cash sale works when title is clouded
- Call (508) 286-7942 or send the address through our cash offer form. Tell us anything you already know: a judgment, a contractor dispute, unpaid taxes, a name on the deed that should not be there.
- We look at the house and price it on condition, the same as any other property. Title problems affect the path to closing, not usually the number.
- A written cash offer within 24 hours.
- An as-is purchase and sale agreement, with language about delivering clear, marketable title and paying recorded claims from proceeds rather than out of your pocket. Whether you want your own attorney is up to you, and our take on that question is that a second set of eyes is rarely a bad investment.
- The title exam runs. This is the moment of truth: the attorney searches the Registry of Deeds, pulls the municipal lien certificate, and produces the actual list. Sometimes it is shorter than the seller feared. Sometimes something old turns up. Either way you will hear it from us straight.
- Payoffs and releases are gathered. Municipal figures usually come back quickly; state and federal releases generally take longer, which is the single biggest factor in choosing a closing date. This is where we adjust the schedule rather than the price.
- Closing. Each payoff appears as a line on the settlement statement, the deed records, the releases record, and the balance comes to you by wire or bank check. The cash closing process step by step shows the same sequence, and how it works gives the short version.
Three ways to deal with a clouded title
| Path | Typical timeline | Out of pocket before closing | Certainty |
|---|---|---|---|
| Cash sale to us, as-is | Written offer in 24 hours; closing paced by the slowest payoff or release | None — payoffs come from proceeds; no repairs, no commission | High: no lender to satisfy, and we do not walk over title surprises |
| Clear the liens yourself, then list | Weeks or months of correspondence before listing | Attorney time, and any payoff you fund yourself | Moderate: cleaner title, but the market and the buyer’s lender still decide |
| List first and hope it clears | Time on market, then the buyer’s timeline on top | Repairs and prep, commission at closing | Low: title surprises commonly blow up financed deals at the last minute |
What we need from you
- The address, and the names exactly as they appear on the deed.
- Any paperwork you have: judgments, demand letters, a notice of contract from a contractor, IRS or DOR notices, condo association statements.
- Whether anyone on the deed has died, divorced, or cannot be reached.
- Mortgage and home equity line information, including anything you suspect was never discharged.
- One walkthrough. Our guide to the paperwork a Massachusetts sale requires lists what the attorney will eventually want.
The honest part: the offer is below full retail, and timing is the real variable
Our cash offer is below what the house would sell for fully repaired on the open market. We take on the repairs, the holding costs while the work runs, the resale costs, and the risk, and the offer has to make room for that. What is different about this situation is that the title problem itself is usually not what moves our number much — it moves the calendar. A state release or a federal discharge takes as long as it takes, and we would rather build a realistic date into the agreement than promise you seven days and miss it.
On the net: whichever way you sell, the recorded claims get paid from the proceeds, so the honest comparison is what is left afterward. A listing starts higher and then subtracts the commission, repairs, an inspection credit, the deed excise, and months of carrying costs — and it carries the extra risk that a financed buyer walks when the title exam surfaces something. Our number has no commission and no fees, we cover the typical closing costs, and we do not withdraw when the search comes back complicated. If the liens exceed what the house is worth, we will tell you that early; what happens when you owe more than the house is worth covers the realistic outcomes.
A clouded title is a problem with a process, not a dead end
Nearly every title issue we encounter has been encountered before by someone whose job it is to fix it. Missing discharges get chased down. Mechanic’s liens get released or bonded over. Estates get opened and personal representatives appointed. Payoffs get negotiated. It is paperwork and patience far more often than it is litigation.
We buy houses with complicated title across the state, including Boston, Worcester, Lynn, and every neighborhood in Suffolk County. This page is general information and not legal advice; outcomes depend entirely on what is recorded against your property, so please have a Massachusetts attorney review your records before you decide anything.
If a lien has your house feeling frozen, call (508) 286-7942 or request a no-obligation cash offer. You will have a written number within 24 hours, an honest read on what the title work is likely to involve, and no obligation to go further. We are family-owned, based in Norton, and we have bought 230+ homes in Massachusetts.
Three simple steps to a cash sale
Selling to us is straightforward and honest — here’s exactly how it goes.
Tell us about your house
Share a few details by form or phone — it takes about two minutes. No pressure, no obligation.
Get a fair cash offer
We review your home and recent local sales, then call you with a clear, no-obligation cash offer within 24 hours.
Close on your date
Accept and pick your closing date — as fast as 7 days, or whenever works for you. No repairs, no fees.
Selling to us vs. listing with an agent
A fast, certain, fee-free sale — with an honest look at the trade-off on price.
| Comparison factor | New England Home PartnersDirect cash buyer | Listing with an agent |
|---|---|---|
| Time to close | As fast as 7 days | 60–90+ days |
| Repairs & cleanup | None — we buy as-is | Often expected before listing |
| Showings | None | Multiple, on the buyer’s schedule |
| Fees & commissions | $0 | ~5–6% commission |
| Closing costs | We cover them | Typically paid by the seller |
| Financing fall-through risk | None — we pay cash | Common with buyer mortgages |
| Sale price | A fair cash offer (below full retail) | Potentially full retail — after fees, repairs & time |
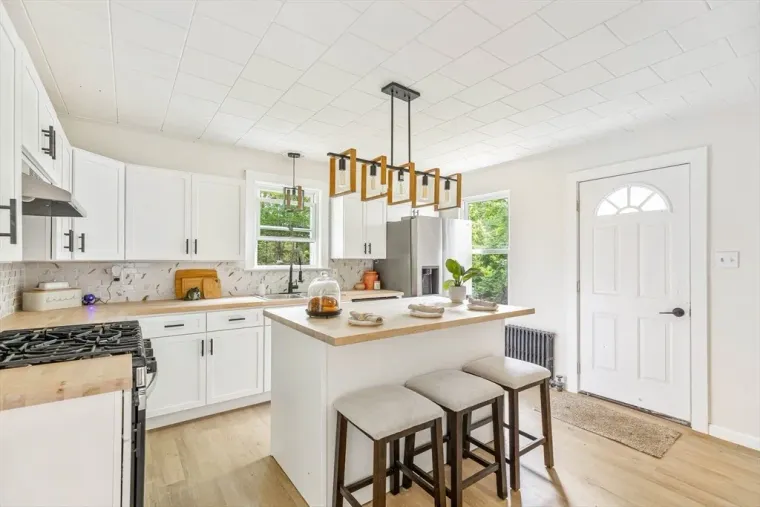
We actually buy and fix these homes
We’re not wholesalers flipping contracts. Here are real homes we’ve purchased and renovated.
Related guides
Plain-language Massachusetts guides that go deeper on the parts of this that matter most.
Other situations we buy houses in
Whatever is behind the sale, the process is the same — we buy as-is for cash across Massachusetts, on the date you choose.
Inherited a house
Probate-friendly, as-is, split easily among heirs.
Facing foreclosure
Move fast to stop the clock and protect your credit.
Going through divorce
A clean, fast sale that splits cleanly between parties.
Relocating
Sell on your schedule when a job or move comes up.
Tired landlord
Done with tenants and turnover? Sell with them in place.
House needs repairs
No fixes, no cleanup — we buy in any condition.
Downsizing
A simple, low-stress sale for the next chapter.
Vacant property
Stop paying to hold an empty house you don’t need.
Owe back taxes
Behind on property taxes? We can close before a tax taking.
Behind on payments
Behind on the mortgage? Sell to avoid foreclosure and protect your credit.
Fire-damaged house
We buy fire- and smoke-damaged homes as-is — no rebuild needed.
Water-damaged house
Flood, leak, or burst pipe? We buy as-is, mold and all.
House with mold
Mold problems? We buy as-is — no remediation needed.
Hoarder house
Leave everything — we handle the full clean-out.
Liens or title issues
Liens or title clouds? We work through them with you.
Condemned house
Code violations or condemned? We buy as-is and take it on.
Questions homeowners in this situation ask
Can I sell my house if there is a lien on it?
What if I do not know exactly what liens are on the property?
Do I have to clear the title or pay off the liens before I sell?
How much below market value will your offer be?
What if the liens add up to more than the house is worth?
Is this legit? Someone told me to just sign the deed over.
Where we buy houses in Massachusetts
We buy houses for cash statewide. These are some of the cities homeowners contact us from most.
- Sell my house fast in Worcester, MA
- Sell my house fast in Springfield, MA
- Sell my house fast in Lowell, MA
- Sell my house fast in Cambridge, MA
- Sell my house fast in Framingham, MA
- Sell my house fast in Quincy, MA
- Sell my house fast in New Bedford, MA
- Sell my house fast in Brockton, MA
- Sell my house fast in Lynn, MA
- Sell my house fast in Newton, MA
- Sell my house fast in Fall River, MA
- Sell my house fast in Plymouth, MA
Ready for your free cash offer?
No fees, no repairs, no obligation — just a fair, honest offer in 24 hours.